Yes, a roofer can talk to the insurance adjuster about the roof: the damage, the measurements, the estimate and how the repair gets done. What a roofer can't do without a license in many states is negotiate the settlement or speak for the homeowner on the claim. The trouble is that the line moves by state, and in Iowa two official sources draw it in different places.
I build CRM For Claims, software for roofing and restoration companies working insurance claims. I'm not a lawyer, and this isn't legal advice. On November 5, 2026 I read the regulators' documents and the newest federal ruling, and this is what I'd hand a sales rep before the next inspection.
Can a roofer talk to the adjuster at all?
In the states I read, a roofer may be present and answer questions about the estimate, at least by the regulator's own guidance. Negotiating is the part no source allows. Oklahoma and Iowa both publish lists, and Iowa's highest court then read the same law more narrowly on several of the same acts.
| What the roofer does | Regulator lists | Iowa Supreme Court, 2020 |
|---|---|---|
| Tell the owner the damage looks like storm damage | Allowed in Oklahoma and Iowa | Not named in the court's list |
| Suggest filing a claim | Allowed in both | Counts as advising the insured |
| Write the estimate | Allowed in both | The court's list names submitting it, below |
| Send the estimate to the insurer | Oklahoma: the insured may submit it. Iowa, 2024: only if asked | Counts toward aiding a settlement |
| Attend the adjuster's inspection | Allowed in both | Counts toward aiding a settlement |
| Answer the adjuster's questions | Allowed in both, in Iowa about the estimates | Discussing the repair with the insurer counts |
| Negotiate the amount | Needs a public adjuster license | Prohibited |
Sources, so you can read them yourself: the Oklahoma Insurance Department notice of May 27, 2010, the 2021 Iowa commissioner's order as quoted on the Merlin Law Group blog, the Iowa Insurance Division release of December 2024, and the court's reading as the Eighth Circuit summed it up. The order came after the court's decision, so an Iowa contractor has a list from the regulator and a harder sentence from the court. Ask a local attorney which one you can lean on.
Texas points the same general way. Its Department of Insurance FAQ lets a roofer discuss the scope of the repair estimate with the consumer or the insurer, and it requires a license to advertise adjusting claims. It also says a licensed public adjuster can't act as one on a property where they provide or may provide roofing.
The stakes are real. In Iowa, acting as an adjuster without a license is a class D felony, or class C if the loss is over $10,000, and a contractor can be fined up to $40,000 per violation under the residential contractor section. Those figures come straight from the opinion below.
What did the Eighth Circuit change in August 2026?
It kept Iowa's two statutes standing and rejected the vagueness argument, so nothing here licenses a roofer to negotiate. But it said Iowa regulated speech when it warned one roofer over certain marketing sentences. Those warnings now face strict scrutiny, and the trial court has to look at them again.
The words from Iowa's warning notices that the court looked at:
- "assist with insurance claims"
- "navigate the insurance red tape"
- "assist [them] with the claims process"
- "walk[] [them] through everything with insurance reimbursement"
The case is Shamrock Hills v. Iowa, No. 25-2991, filed August 12, 2026. Read it closely before you put those phrases back on your website. The roofer hasn't won anything yet: the panel wrote that it remains to be seen whether the company can prove its allegations, and one judge wouldn't have reached this question at all. The same opinion says that, when tied to settling a claim, assessing damage, preparing estimates, reviewing policies, evaluating coverage and submitting claims all appear to fall within the Iowa statute.
Two more limits on how far it travels. An Eighth Circuit ruling doesn't bind courts in Texas, where the state supreme court upheld the Texas rule in 2024 in the Stonewater Roofing case. And it was decided on a motion to dismiss, so no court has yet ruled on the facts.
Sentences your rep can say, and ones to drop
This sort is my own judgment from the sources above, so run it past your attorney once and then put your version in your training. The test I used: is the sentence about the roof and the repair, or about the policy and the money?
About the roof, so generally safe
- "Here's the measurement report. That slope is 11 squares."
- "These are my photos of the bruising on the north slope."
- "That line in my estimate covers tear-off of two layers, because I found two layers."
- "The manufacturer's install instructions call for starter here, and here's the page."
Depends on your state, so check first
- "I think you should file a claim." Allowed on the regulator lists, counted as advising by the Iowa court.
- "I'll email the adjuster my estimate directly." Safer when the homeowner sends it or the adjuster asks for it.
- "I'll be there when the adjuster comes." Same split, as the table shows.
About the policy and the money, so licensed work
- "Your policy has to pay for this."
- "I represent the homeowner on this claim."
- "We won't accept that number, so come up to mine."
- "Sign this and I'll handle the insurance company for you."
Writing to the carrier is where this usually goes wrong, because an email feels like paperwork. In one 2024 Iowa consent order reported by Roofing Contractor, the state described a roofer asking the carrier to change a material code and add 10% overhead and 10% profit, then asking for a corrected estimate. If you're chasing overhead and profit on a roof claim in a state like that, the homeowner or a licensed adjuster makes the request, using your numbers.
One inspection, played out
The turn usually comes on the roof itself, when the adjuster offers a trade. This roof and its numbers are made up, and in a state that follows the Iowa court you may want counsel's view before you attend at all.
- Adjuster
- I've got 24 squares. You wrote 28.
- Rep
- My report includes the back porch roof, which is 4 squares. It's on page two, with the photos.
- Adjuster
- Okay, I'll look at the porch. Would you take 26 if we leave the gutters alone?
- Rep
- I can't speak to a settlement. That's between you and the homeowner. I can tell you what the gutters need: they took dents on the north run, and those are in the photos too.
- Homeowner, later that day
- What did they say?
- Rep
- The adjuster is checking the porch and asked about the gutters. You'll get their estimate. When it comes, I'll compare it to the work I priced and show you any line that doesn't match the repair.
The rep answered three things about the roof and refused one thing about money. If the adjuster wants a second look later, how a reinspection request gets written matters for the same reason, and who signs it is worth settling in your state.
The words on your website, truck and contract
Advertising can be the violation by itself. Oklahoma's notice names roofers who advertise as claim specialists or claim analysts, or who refer to denied claims or deductibles. In Iowa, a roofer's website got attention for listing a staff member as an adjuster, as the Corridor Business Journal reported in 2024. Here are some rewrites to consider.
Our insurance claim specialists
Our roof inspectors and estimators
We deal with your insurance company
We document the roof and write an itemized estimate you can share
Claim denied? We'll fight it
Bring us the denial letter and we'll inspect the roof and tell you what we find
Jim, staff adjuster
Jim, project estimator
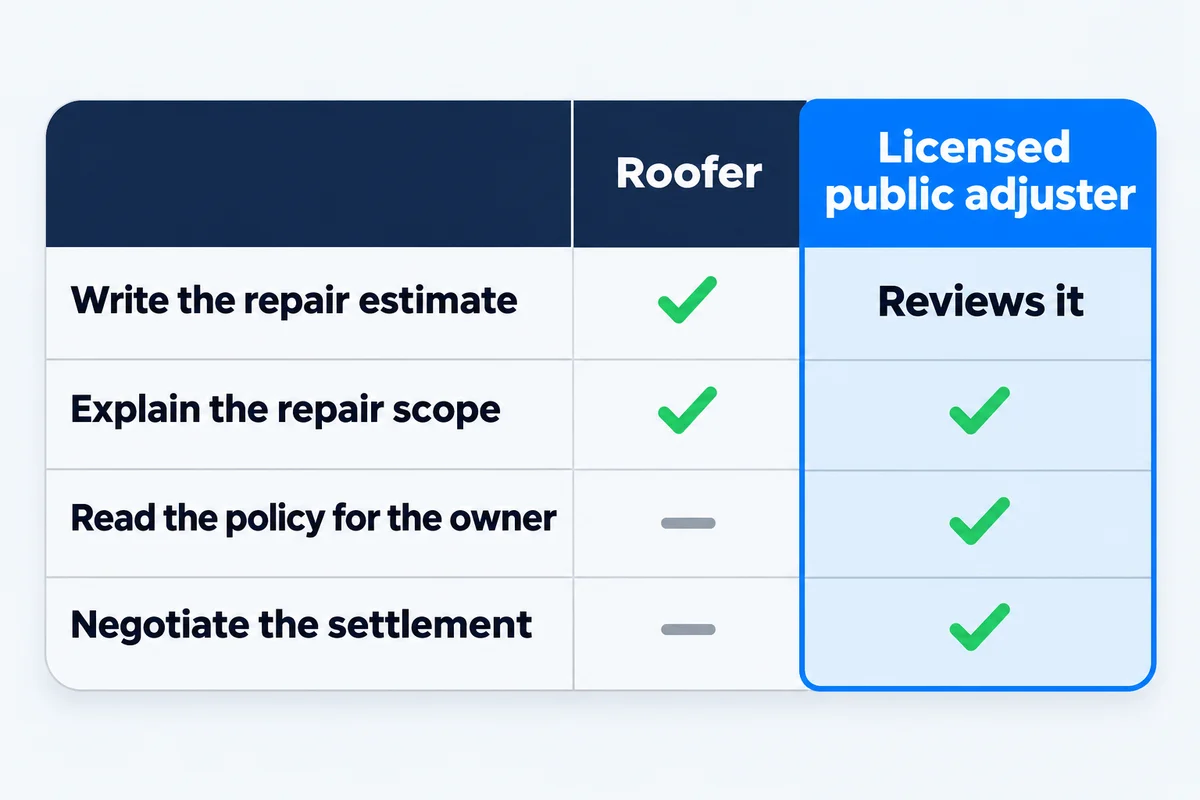
Then read your contract. Oklahoma treats a contractor as a public adjuster when they ask the insured to sign a power of attorney or any other contract that authorizes them to act on the insured's behalf for a fee. Look at your roofing contingency agreement line by line for that kind of authority, and have counsel read it for your state.
Who negotiates when the numbers don't match?
The homeowner or a licensed public adjuster does. Iowa says exactly that, and adds that a contractor can't be both the contractor and the public adjuster on one project. Your part is to supply a clean file that either of them can use, and to step back from the conversation about money.
When that moment comes, this public adjuster or attorney handoff is the part you can do well. In Illinois, where we're based, public adjusters are licensed under Article XLV of the Insurance Code and Department Rule 3118, so that's where an Illinois roofer's attorney would start. Elsewhere, start at your own department of insurance, since a 2010 notice or a one-state ruling may not describe your market.
Keeping the record of what was said
If a regulator or a carrier ever asks what your company said, the answer is only as good as the file. Train it once, as part of training a new hire on your claim process, and keep the proof on the claim.
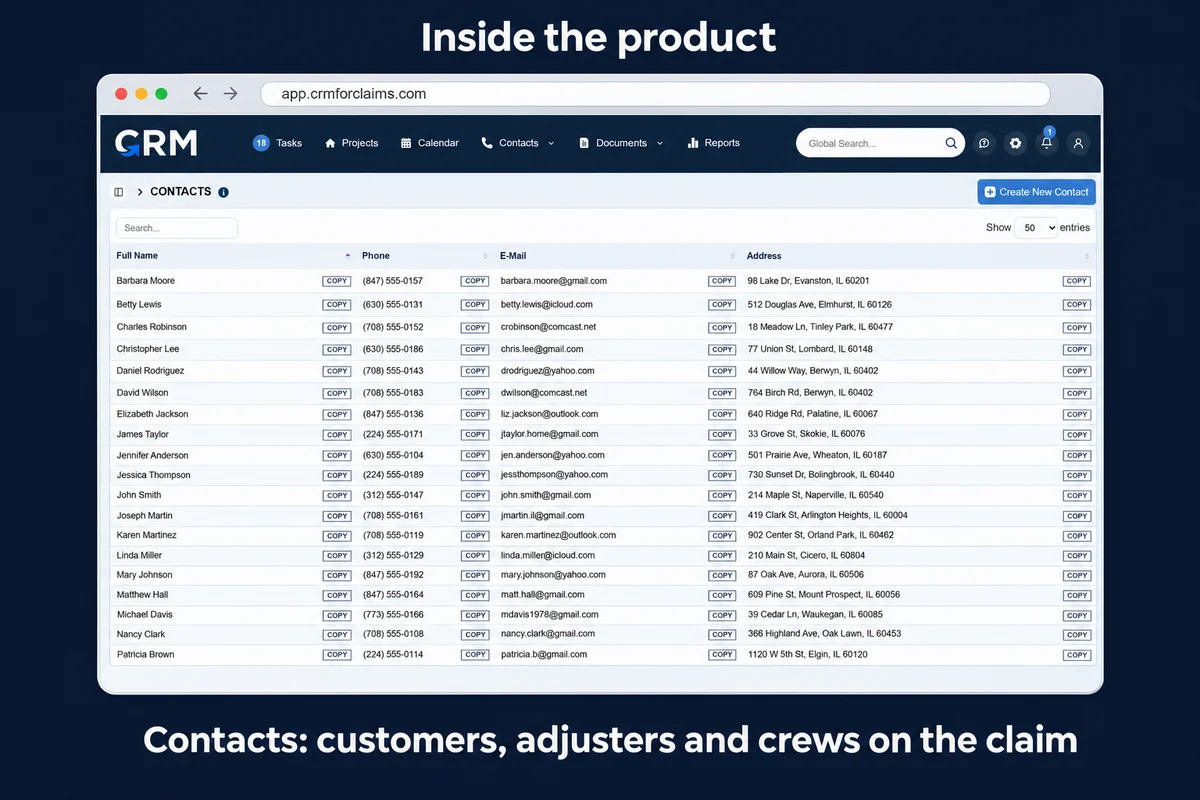
On a claim in CRM For Claims, you can search for and add the field adjuster on that record. The same record has a separate field for the inside adjuster. The Email Communication folder is there to hold a copy of all email, phone and text communications on the project. Measurements has its own folder on the project too. A workflow stage can create a task when a project enters it, so the rep can be handed a reminder to review the rules before an inspection.
The full list is on the CRM For Claims features page. If you want to see it against a real inspection day, book a live walkthrough and bring the way your office handles carrier email today.